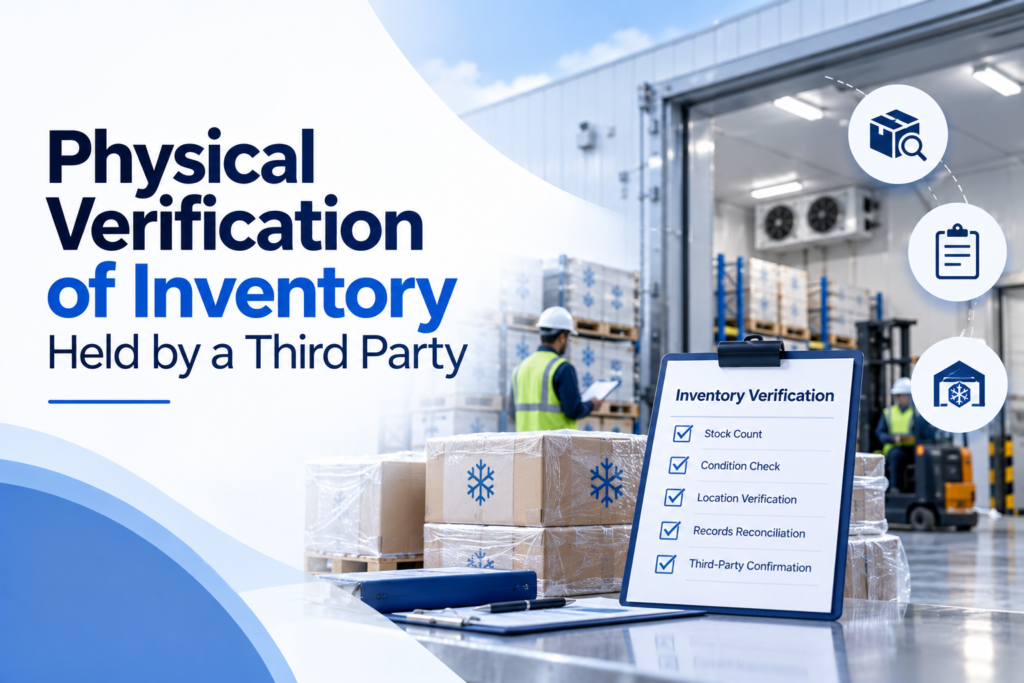
Stock held in a 3PL cold store can be verified by third-party confirmation, by inspection, or both. Under SA 501, where that inventory is material, the auditor chooses procedures to get sufficient evidence of quantity and condition. In a frozen chamber, plan the count before year end so it does not warm the stock.
For a finance controller at a frozen food or dairy brand, the year-end question is practical. Who counts, when, and with what records?
This guide explains the standard in plain terms and shows how to run a count in a frozen chamber. It also lists the records to ask your 3PL for.
| Physical verification of inventory held by a third party (definition) It is the process of obtaining evidence that stock held at another party’s warehouse exists, in the quantity and condition your books show. Under SA 501, the auditor can request confirmation from the third party, inspect the stock, or perform other appropriate procedures. |
TL;DR
- SA 501 covers inventory held by a third party when it is material.
- The auditor can request confirmation, inspect the stock, or do both.
- CARO 2020 clause 3(ii)(a) covers management’s own verification and a 10% discrepancy test by class.
- FSSAI expects storage and distribution records to be kept for one year or the shelf life, whichever is longer.
- A full count in a frozen chamber is also a temperature event, so it needs a plan.
- The Year-End Count Plan sets cut-off, sampling, entry limits and reconciliation.
- Most differences come from in-transit, damaged, quarantined or expired stock.
- Next step: agree the count method with your auditor and your 3PL before year end.
→ Ask Coldman which stock records it provides for audit support
What Auditors Must Report on Inventory Held by Third Parties
A statutory auditor reviewing a frozen food brand’s stock at a 3PL looks to SA 501, Audit Evidence: Specific Considerations for Selected Items. Where such inventory is material, the auditor must obtain sufficient appropriate evidence. The auditor can request confirmation of quantities and condition, inspect the stock, or use other procedures, per an ICAI SIRC presentation on SA 501.
Separately, CARO 2020 clause 3(ii)(a) asks whether management verified inventory at reasonable intervals. It asks about discrepancies of 10% or more in aggregate for each class of inventory, per BCAJ’s guide. Ask your auditor how third-party stock fits into that clause for your company.
Confirmation, Count or Both
The assumption is that stock at a 3PL must be counted pallet by pallet. The reality is that SA 501 gives the auditor a choice. The best method depends on materiality, the provider’s controls and the cost of entry.
For a CFO, a confirmation from the 3PL is the lightest option. A sample count adds assurance for high-value or high-risk lines. Agree the method in writing, because the 3PL needs notice to arrange access and safety.
Why Counting in a Frozen Chamber Needs a Plan
A count inside a frozen chamber is a safety event for people and a temperature event for stock. Open doors let warm air in, and long entries slow the work. A warehouse manager will want short entry windows, protective clothing, and a clear route through racking.
Coldman’s Technology page lists door-operation monitoring and high-speed roll-up doors to limit temperature loss (October 2026). Ask how the provider keeps door-open time down when auditors enter.
Schedule the count for a low-movement window, and agree who enters, in what order and for how long. A planned entry rota protects both the stock and the people counting it.
The Year-End Count Plan for a Frozen Chamber
The Year-End Count Plan for a Frozen Chamber has six steps:
- Agree the count date and time, and the cut-off for movements.
- Freeze movements during the count, or log every one with a time stamp.
- Choose the method: confirmation, sample count by batch and location, or both.
- Schedule short entries with an entry rota, protective clothing and door discipline.
- Reconcile your books, the 3PL’s system and the count.
- Record each difference with a reason and a sign-off.
| ⚠️ Warning Do not run a count while goods are still moving in and out. Late movements create differences that look like stock loss. |
| 💡 Tip for finance teams Ask the 3PL for a stock statement as at the cut-off time before the count begins. Known differences can then be traced before anyone enters the chamber. |
Reconciling Your Books to the 3PL’s Stock Statement
Most differences are timing or status, not loss. The table lists the common breaks and what resolves them.
| Break | What it usually means | Evidence that resolves it |
| In transit | Goods dispatched but not yet received | Dispatch note and receipt time |
| Damaged | Stock held but not saleable | Damage report and photographs |
| Quarantined | Stock on hold for a quality check | Hold record and release date |
| Expired or near expiry | Stock past its use-by date | Batch record and ageing report |
| Mis-picked | Wrong SKU or batch moved | Pick list and dispatch record |
For an accounts executive, each row needs a document.
Clause 8.2 of FSSAI’s Schedule 4, Part II requires storage, distribution and pest control records. Keep them for one year or the shelf life, whichever is more, as set out in FSSAI’s compendium.
What to Ask Your 3PL to Provide
A procurement or finance head can ask for these before year end:
- A stock statement by SKU, batch, expiry and location at the cut-off time.
- Inward, outward and adjustment logs for the period.
- Ageing and quarantine reports.
- The method for supporting an auditor’s visit and confirmation request.
- A named contact for reconciliation queries.
Coldman’s Quality Assurance and Technology pages describe real-time inventory visibility through a web portal and mobile app, automated alerts, and inventory ageing reports (October 2026). Ask Coldman how it supports auditor confirmations and counts, because this post does not state its policy.
→ Ask Coldman for a sample stock statement and its audit-support process
Choosing What to Sample
A sample count works best when it targets risk, not convenience. For an internal audit lead, a risk-based sample covers:
- High-value SKUs and fast-moving lines.
- Batches near expiry or past their ageing threshold.
- Locations with recent adjustments or quarantines.
- Lines with differences in the last count.
- A random sample from the rest, to test the records overall.
Agree the sampling rule with your auditor in writing, so the 3PL can pre-pull batch and location lists.
After the Count: Closing Differences
A count is finished only when every difference has a reason. A finance controller should close each one in order: confirm the count, trace the movement documents, check cut-off, then post any real adjustment with approval.
Share the signed reconciliation with the 3PL and keep it with the audit file. Repeating the same method next year makes the second count faster than the first.
When Confirmation Alone Is Enough, and When Coldman Is Not the Fit
If stock at the 3PL is small relative to your total inventory, the auditor may decide that a confirmation is enough. A brand holding most of its stock in its own warehouse is in that position.
Coldman Logistics is not the right partner for short-term overflow with no contracted volume. Its network page lists nine live sites, and its industries page shows the food lines it serves. Its Quality Assurance page describes the monitoring and reporting that support audit evidence.
The Cost of an Unplanned Count
For a CFO, the cost is a year-end delay and a large unexplained difference in the stock note. The auditor may then ask for a second count in a chamber nobody planned to enter.
Agree the method now, not in March.
→ Talk to the Coldman team about stock records and count support for your audit
FAQs
What is perpetual stock verification?
It is a programme that counts parts of the inventory throughout the year, so every item is verified over a cycle. It relies on accurate stock records and prompt investigation of differences.
What procedures are used in an inventory audit?
Typical procedures include observing counts, confirming stock held by third parties, testing cut-off, comparing counts to records, and checking condition and valuation.
Can an auditor rely on a warehouse’s stock confirmation?
Under SA 501, a confirmation can be sufficient evidence for third-party inventory, but the auditor decides based on materiality and the provider’s controls.
Does a frozen chamber count affect stock temperature?
It can. Long or frequent door openings raise chamber temperature, so plan entry windows and keep a temperature log for the count period.